90 Day Satisfaction Guarantee

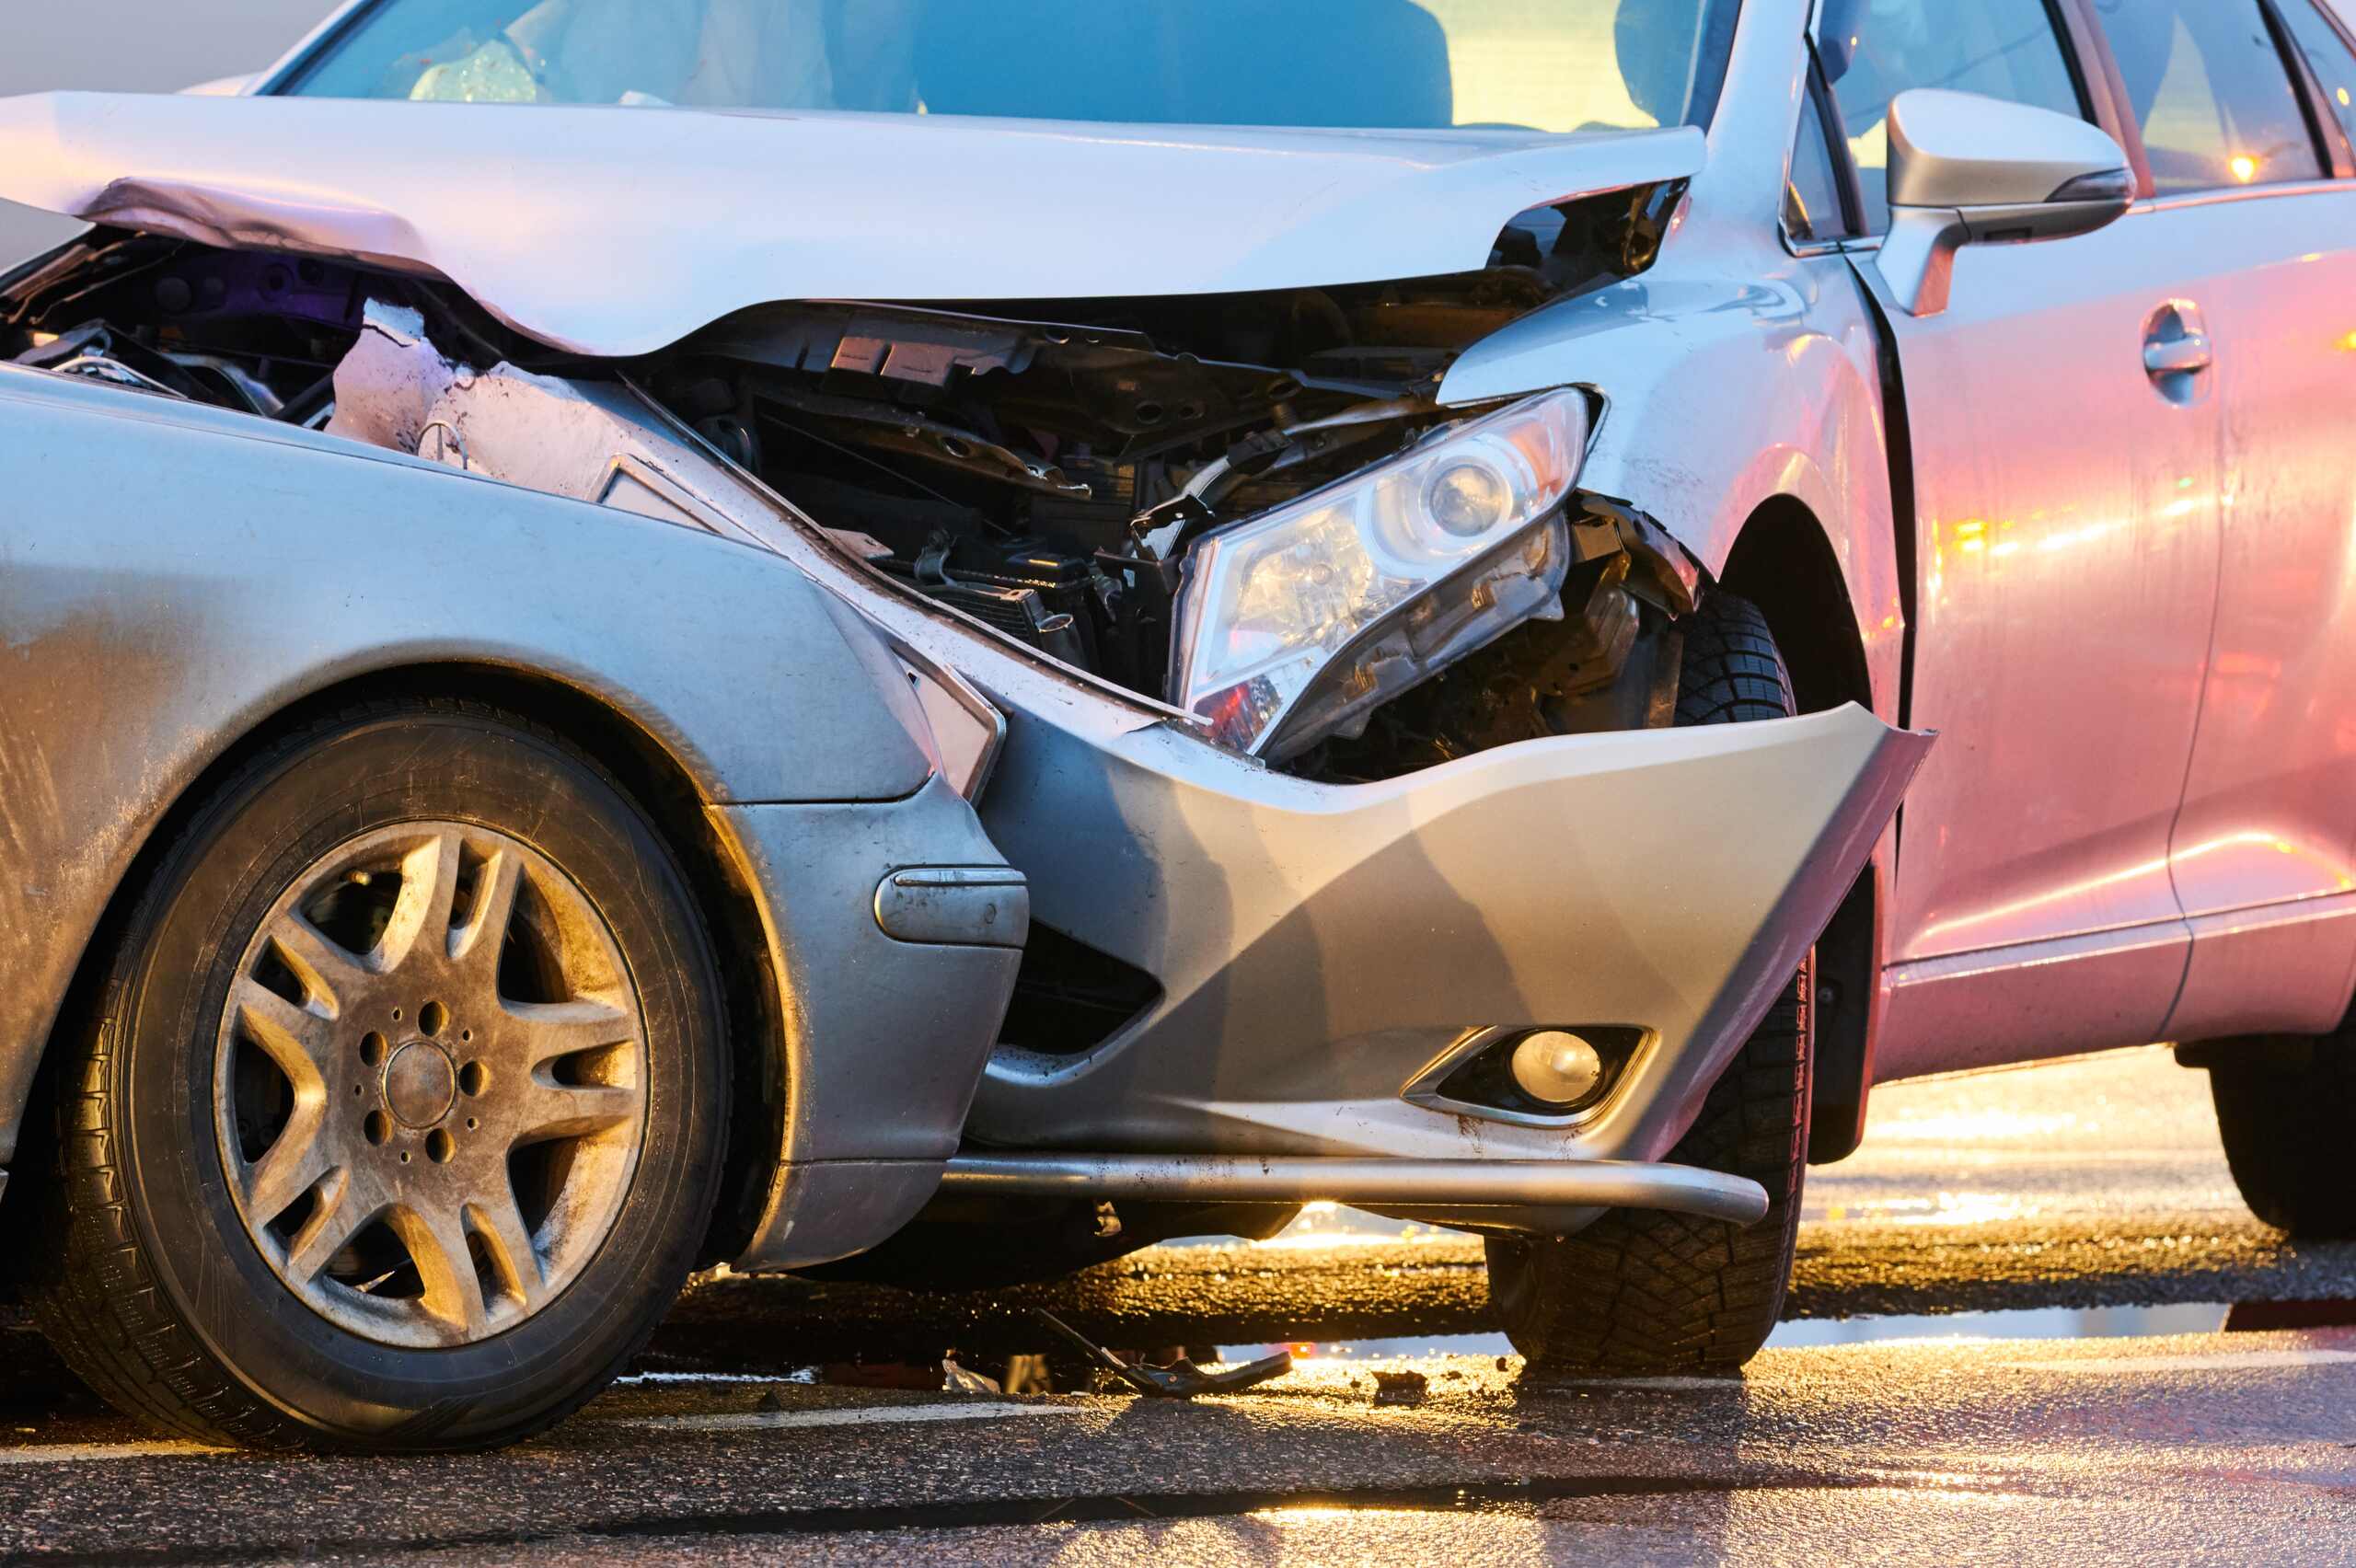
If you searched for the average car accident settlement in Nova Scotia, you have probably found American websites quoting figures that have nothing to do with how claims work here. Nova Scotia has its own insurance rules, its own cap on minor injury awards, and its own way of valuing what a crash takes from you.
This post explains what actually drives car accident settlement amounts in this province, and why two people in the same collision can end up with very different results. If you want a realistic range for your own situation, a car accident lawyer at Wagners can give you one after a free consultation.
The honest answer is that averages mislead more than they inform. A settlement is built from your specific injuries, your income, your prognosis, and the strength of the evidence, so a figure averaged across thousands of different lives tells you almost nothing about yours. Insurers do not negotiate from averages either, and neither should you.
Averages also hide the extremes that distort them. A handful of catastrophic settlements worth millions pulls an average far above what a typical soft tissue claim resolves for, while capped minor injury claims pull in the other direction. The useful question is not what the average is, but which category your claim falls into.
Nova Scotia limits pain and suffering awards for injuries defined as minor under the province's Automobile Accident Minor Injury Regulations. The regulation applies a two-stage test: first, whether the injury is a sprain, a strain or a whiplash-associated disorder injury as the regulation defines it, and second, whether it results in serious impairment. Serious impairment has three requirements and all three must be met, the third being that the impairment is not expected to improve substantially.
The cap was set at $7,500 when the regulation came into force and rises every January with the Nova Scotia consumer price index, with the Superintendent of Insurance publishing the current figure each January. That indexing is why any dollar figure you find online is out of date almost immediately.
The cap applies only to pain and suffering, not to your other losses. Lost wages, loss of valuable services around the home, and out-of-pocket costs remain claimable in full even for a capped injury. This distinction surprises many claimants, and it means a "minor" injury claim can still be worth far more than the cap itself.
Whether an injury is truly minor is one of the most contested issues in these claims. If your symptoms persist, interfere with work, or point to something more serious, the cap may not apply at all. This is often where legal advice changes the value of a claim most dramatically.
Every settlement is a sum of separate categories of loss, called heads of damages. In Nova Scotia, the main heads are:
Adding these together, rather than guessing at a lump figure, is how lawyers and insurers actually value claims.
One thing you will not see on that list is past medical bills. Hospital and physician care in Nova Scotia is covered through MSI, and additional treatment costs flow through your own auto insurer's Section B benefits [internal link]. This is a major reason car accident settlement amounts in Canada look different from the American figures online, where medical bills often make up the bulk of a claim.
Permanent injuries drive the largest settlements because they generate losses that continue for decades. A serious injury at age 30 can mean 35 years of reduced income, and courts compensate that full span. Future earning capacity, not pain and suffering, is usually the biggest number in a major claim.
Canadian law caps general damages for pain and suffering even in catastrophic cases, following a trio of Supreme Court of Canada decisions in 1978. Those decisions set the ceiling at $100,000 and it has been indexed for inflation ever since, so the working figure is several times that today and is reserved for the most severe catastrophic injuries. No such cap applies to income loss or future care, which is why total settlements in catastrophic cases can reach into the millions.
Between the minor injury cap and the catastrophic ceiling sits the broad middle ground where most contested claims live. Claims in that range are valued by comparing prior Nova Scotia decisions with similar facts, which is slow, unglamorous work and the only method that produces a number either side can defend. Persistent whiplash claims that cross the line out of the minor injury definition fall into this territory.
Nova Scotia reduces a settlement by the claimant's own percentage of fault. Under the province's Contributory Negligence Act, a person found 25 per cent responsible for a collision recovers 75 per cent of their assessed damages. Fault arguments are common in intersection crashes, left-turn collisions, and cases involving road conditions.
Not wearing a seatbelt can also reduce an award, even when the other driver caused the crash entirely. These arguments come up routinely, and every percentage point of fault changes what the claim is worth. Pushing back on inflated fault allegations is a quiet but significant part of settlement negotiation.
Not before your medical picture is clear, in almost every case. A settlement is final, so accepting an offer while your prognosis is still uncertain means absorbing any future deterioration at your own expense. Early offers can arrive before the medical picture has settled, which is the point at which a claim is hardest to value.
Timing pressure runs in the other direction too. Nova Scotia's Limitation of Actions Act generally gives you two years from the date you knew or ought to have known you had a claim to start a court action. Missing that window can extinguish the claim regardless of how strong it is, so the safe path is getting advice early and settling late.
Wagners has been valuing and litigating Nova Scotia injury claims from our Halifax office since Ray Wagner founded the firm in 1982. Our lawyers are recognized by Best Lawyers and ranked by Lexpert. We work from what Nova Scotia courts have awarded in comparable cases, because prior decisions are the real benchmark, not averages.
We act on a no-win, no-fee basis and serve clients across the province, from Halifax and Dartmouth to Cape Breton, the Valley, and the South Shore. When we give you a valuation, it comes from comparable cases and a full accounting of your losses. That number is the starting point for negotiation, and we prepare every file as if it may need a courtroom to finish.
Settlement value questions tend to come with practical follow-ups, so here are answers to the ones this post has not already covered.
Straightforward claims often resolve within one to two years, while serious injury claims commonly take two to four years or longer. The biggest factor is how long your recovery takes to stabilize, since settling before then risks undervaluing the claim. Litigation deadlines and court schedules can extend the timeline in contested cases.
Personal injury settlements for pain and suffering and most related damages are generally not taxed as income in Canada. Interest or investment income earned on settlement funds afterward is treated differently. A tax or financial adviser can confirm how the rules apply to your specific settlement structure.
Claiming against an at-fault driver's insurer is not the same as an at-fault claim on your own policy. Using your own Section B benefits, which are no-fault, is a standard part of the process. Rate questions depend on your insurer and fault determination, so ask your broker how your policy treats not-at-fault claims.
Nova Scotia policies include Section D coverage for collisions with uninsured or unidentified drivers, and many policies add an SEF 44 endorsement for drivers who are insured but underinsured. These claims carry their own notice requirements and timelines, and a hit and run brings extra reporting obligations on top. Acting quickly matters more here than in almost any other claim.
The large majority settle through negotiation, often after discovery, the pre-trial stage where both sides exchange documents and question each other under oath. Filing a court action is common even in claims that eventually settle, because it preserves the limitation period and moves negotiations forward. Trials are the exception, reserved for claims where the two sides remain far apart.
Yes, the law compensates you for how the crash made your condition worse, even if it did not cause it originally. The effect of a prior condition is often disputed, so medical records from before the collision become important evidence. A well-documented "before and after" picture is usually the answer to this defence.
Yes, passengers can claim against any driver whose fault contributed to the crash, including the driver of the vehicle they were riding in. Passengers are rarely assigned fault, so their claims often face fewer deductions than a driver's claim from the same collision. The same minor injury cap and heads of damages apply to passenger claims as to any other injury claim.
Averages will not pay your bills, and they will not tell you whether an insurer's offer is fair. A file review will, so send us the basics of your collision and injuries and a Wagners lawyer will walk you through the categories of loss that apply to you and the range comparable Nova Scotia cases support. The consultation is free and carries no obligation, so reach out to Wagners and start with a range grounded in decided cases rather than a guess.